The EU: A Prescription for More Stagnation (or Worse)
National Review Online, October 31, 2024
In July 2007, José Manuel Barroso, the president of the European Commission (Brussels’ top bureaucrat) said rather a lot of the quiet part aloud. The European Union, he boasted, was an empire, an empire of new kind, a “non-imperial empire,” but an empire all the same. For some that had always been the idea. Europe’s former great powers could never, individually, restore the global preeminence they had enjoyed before the world wars. Maybe they could come close to doing so collectively. A united Europe could become a rival “pole” to the U.S., not an enemy, not militarily, but economically and as an exemplar to the rest of the world of a better way forward.
After the USSR collapsed, hopes grew that that glorious day was dawning. Évidemment, the American “cowboys” had been helpful in seeing the Soviets off (merci!). But with the construction of an international rules-based order (supposedly) well underway, Yankee weapons and military did not matter quite so much. The soft power flowing from the EU’s (supposedly) superior social and economic model would propel it to the top table. Supposedly.
The wars after 9/11 and the growing assertiveness of Russia and China were rude reminders that the old hard-edged geopolitics could not safely be consigned to the past. Despite ever louder warnings from the EU’s eastern members and grumbling from the U.S., too many European countries continued to behave as if history had ended with the fall of the Soviet Union. They skimped on defense, and, in many cases, left their economies dangerously dependent on “cheap” Russian gas. Germany, the EU’s economic engine and its largest member state, went further than most. It underspent on defense and it did not let the first invasion of Ukraine stand in the way of its plans to be at the other end of a new pipeline that would deepen its dependence on Russian energy. Berlin’s confidence in Wandel durch Handel (the notion that increased trade would with the West would transform authoritarian regimes), encouraged German companies to focus on opportunities in China. There were 1.3 billion people within its borders, eager to consume! “Win-win,” said Chancellor Merkel.
The EU underestimated the continuing need for hard power, but the economic growth required to underpin its soft power was underwhelming. As was recently noted in The Economist:
In 1990 America accounted for about two-fifths of the overall GDP of the G7 group of advanced countries; today it is up to about half…. On a per-person basis, American economic output is now about 40% higher than in western Europe.
Insult has been added to injury by America’s outperformance in the tech sector. In its Lisbon agenda(2000), the EU gave itself the goal to “become the most competitive and dynamic knowledge-based economy in the world” by 2010. It didn’t work out.
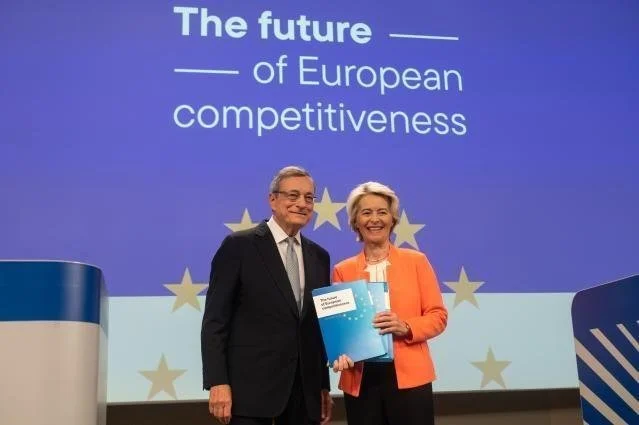
Even the lackluster Ursula von der Leyen, the president of the EU Commission (and another part of Merkel’s legacy) started to worry. A little over a year ago, she asked Mario Draghi, a former president of the European Central Bank, to write a report suggesting how to revive the bloc’s flagging competitiveness. But by choosing Draghi she sent a signal that she was not looking for recommendations that might prove too unsettling. Above all, nothing must challenge the EU’s most hallowed principle, that of “ever closer union.” The solution must be “more Europe,” not less.
In that respect, “Super Mario”, whose impressive resume also includes a stint as Italy’s prime minister, was the right pick. He did whatever it took to save the euro, but does not appear to have given any serious consideration to alternatives such as (to me) the more rational option of splitting the ill-conceived single currency into “northern” and “southern” units. Brussels understands the long game. Progress towards ever closer union can be paused. But any reversal — and splitting the euro would be a reversal — is anathema.
Draghi’s report has now been published. It contains some sensible ideas but leaves untouched too many orthodoxies incompatible with a serious increase in the bloc’s competitiveness. But at least Draghi was willing to admit how far the EU had fallen behind:
A wide gap in GDP has opened up between the EU and the US, driven mainly by a more pronounced slowdown in productivity growth in Europe. Europe’s households have paid the price in foregone living standards. On a per capita basis, real disposable income has grown almost twice as much in the US as in the EU since 2000.
He puts much of the blame on the bloc’s failure to keep up with the U.S. on the area in which the agenda-setters of Lisbon had focused their attention, the tech sector:
Technological change is accelerating rapidly. Europe largely missed out on the digital revolution led by the internet and the productivity gains it brought: in fact, the productivity gap between the EU and the US is largely explained by the tech sector. The EU is weak in the emerging technologies that will drive future growth. Only four of the world’s top 50 tech companies are European… the EU’s global position in tech is deteriorating: from 2013 to 2023, its share of global tech revenues dropped from 22 percent to 18 percent, while the US share rose from 30 percent to 38 percent.
[B]etween 2008 and 2021, close to 30% of the “unicorns” founded in Europe – startups that went on the be valued over USD 1 billion – relocated their headquarters abroad, with the vast majority moving to the US.
Moreover, “we import over 80 percent of our digital technology.”
None of this will bother Brussels’s (and Beijing’s) useful idiot, the FTC’s Lina Khan, a central planner set on reordering America’s tech sector. But might it lead some “Khanservatives” — Senator Josh Hawley and all the rest — to think again? Probably not. Their fondness for big government has different ideological roots to Khan’s, but the shared delusion that they know best is too enjoyable to be abandoned.
But Draghi’s adhesion to orthodoxy is the wrong response at the wrong time. If the EU is to start catching up, it will have to do so in a much more difficult environment than in the recent past. Mounting geopolitical tensions have disrupted the bloc’s energy supplies. Beyond that, they are forcing countries to reevaluate their trade policies, an area in which the EU is more vulnerable than the U.S. or China. Draghi notes that “the EU’s trade-to-GDP ratio exceeds 50 percent, compared with 37 percent in China and 27 percent in the United States.” Supply lines are less secure, previously profitable economic interdependence can be a source of dangerous dependence, and competition has increased: to take one example, the ECB has found that the “share of sectors in which China is directly competing with the euro area exporters is now close to 40 percent, up from 25 percent in 2002.”
Fixing this will take a substantial increase in productivity, and that will require a substantial increase in (successful) investment. But EU already faces substantial calls on its capital, including “decarbonizing” the economy, and, in a dangerous age, boosting the bloc’s defense capacity. Draghi reckons that overall EU investment will:
[H]ave to rise by around 5 percentage points of GDP to levels last seen in the 1960s and 70s. This is unprecedented: for comparison, the additional investments provided by the Marshall Plan between 1948-51 amounted to around 1-2% of GDP annually.
If Europe cannot become more productive, we will be forced to choose. We will not be able to become, at once, a leader in new technologies, a beacon of climate responsibility and an independent player on the world stage. We will not be able to finance our social model. We will have to scale back some, if not all, of our ambitions.
That list of priorities goes quite some way to explaining why the EU will not reach the goals that Draghi has set for it. Take “investment” in decarbonization. Ideally, the response to a changing climate would comprise adaptation (such as the building of greater protection for low-lying cities), investment in low-emission energy sources that do work (such as nuclear), and increased spending on research into effective alternative energy technologies. Instead, the EU’s leaders are participants in a reckless “race” to net zero greenhouse gas emissions by — suspend disbelief here — 2050. This revolves around ploughing billions into the installation of technologies that are not ready for prime time (wind power is probably the most egregious example) and may never be so. Spending on inadequate technologies and the massive infrastructural development required to support them is an exercise in capital destruction, malinvestment, not investment.
Such spending is more likely to send growth into reverse than to increase it, with, paradoxically, consequences likely to hinder rather than help the effort to adapt to or even manage a changing climate. The more wealth that is created, the more there will be to spend on dealing with whatever the climate may throw in our direction. That’s been true throughout history, and it is true now. The less growth there is, the less resilient the EU will be.
Draghi criticizes aspects of how decarbonization is being managed but does not dispute that the “race” to net zero must still be run. It will make little difference to the climate, but, due to the hardship and disruption that it will bring in its wake, it is a clear danger to the EU’s social and economic order. To some climate fundamentalists, the latter is a feature, not a bug (red and green can go well together), but Draghi seems not to care.
This is an act of cowardice and/or complicity that reminds us that, as with his disastrously successful defense of the euro, Draghi masquerades as someone having the answer to the EU’s dysfunction, when, in reality, he reinforces it. And so, rather than advise a switch away from the destructive futility of net zero, he wants to devote more resources to it, a strategy with unsettling echoes of the thinking that led to Passchendaele and the Somme.
During a must-read article for Law & Liberty on Draghi’s report, Samuel Gregg gives an indication of what the cost of the pursuit of net zero will be for Germany, a country already hobbled by climate policy, among other woes:
In an October 2023 report, the University of Cologne’s Institute of Energy Economics estimated that the cost of decarbonization for Germany between 2024 and 2030 would be just over €1.9 trillion in private investment and public spending, with the private sector bearing an ever-increasing share of the cost. That translates squarely into less private-sector productivity.
The self-crippling of substantial parts of many European economies in the name of combating climate change, and the associated failure of the promised green businesses and green jobs to materialize on any meaningful scale, is one of the major economic stories of our time.
It is becoming a major political story too. The populist right’s strong showing in the EU’s parliamentary elections earlier this year, followed by its advances in elections in France, Austria, and three German states owed more to anger over mass immigration (the product of another misguided elite orthodoxy) than discontent over climate policy, but the adverse consequences of the former have had far longer to make themselves felt. Nevertheless, it says something that the Greens fared poorly in these elections.
It says something else that the EU Commission and, indeed Draghi, seem set on ignoring the warning sent by the voters to the bloc’s climate commissars. There are some signs that the EU and its member states are adopting a tougher line on immigration. But if they take as long to quit or at least slow down their race to net zero, they will have to tackle the problems caused by immigration at the same time as climate policy inflicts severe damage on their economies, a toxic combination to say the least.
Draghi’s recommendation that the EU should aim to incorporate a successful and profitable green “transition” within a broader industrial policy is no more than a stacking of illusions. While there is no doubt that a commonsense response to the exceptional economic and geopolitical challenge posed by China will require greater state intervention than would normally be desirable (as Adam Smith would have understood), that should be viewed as a defensive necessity. It will not be the basis of the revived growth that the EU needs. A bunker is not a launchpad.
More generally, if Draghi believes that both China and Biden’s America demonstrate that industrial policy overseen and underwritten to a greater or lesser extent by the state is a pathway to greater prosperity, he has not understood what is going on in either country. China was never moving toward a conventional market economy, but Xi has moved it to something much closer to a fascist economicmodel in which a harnessed capitalism is put to work at the service of a party-state. Even if we disregard China’s current economic woes (and we shouldn’t), that is not a model to emulate.
Meanwhile, such successes as Biden’s industrial policy have generated are mostly the function of the vast sums of (borrowed) money poured into it. Many of the positive numbers seen up to now reflect input, not output. But an investment in a factory is of little or no value if there are not enough customers for what is manufactured there. There is also the question of opportunity cost. Do the government’s inducements to invest in its favored projects mean that capital is being lured away from inherently more valuable projects that the private sector might have otherwise chosen? To ask the question is to answer it.
And government money often comes with strings unrelated to profitability or efficiency, all too often driven by cronyism, ideology or a mix of the two. Thus, applicants for money under the CHIPS program must, among many, many other requirements:
[C]reate opportunities for minority-owned, veteran-owned, and women-owned businesses; demonstrate climate and environmental responsibility [and] invest in their communities by addressing barriers to economic inclusion…
Gregg lists other familiar objections to industrial policy:
Once set in place, industrial policies are notoriously hard to terminate, even when the failure is manifest. The recipients don’t want government assistance to stop, and no political leader or bureaucrat wants to concede failure.
More generally, applying industrial policy to a sector inevitably involves government officials making choices about which companies in that sector are given assistance and which are not. Therein lies the inescapability of industrial policy’s problems. The temptations of collusion and cronyism are irresistible, but even scrupulously honest governments could not know everything they would need to know to identify in advance which companies will succeed.
The result, he concludes will be “inefficient allocations of capital on a mass scale and therefore less productivity: the converse of what Draghi is aiming for.”
Draghi’s reassurances that this can be avoided by “rigorous monitoring” are made even less credible by the nature of the EU’s governing ideology, a mixture of Christian and Social Democracy, two ideologies with little tolerance for letting markets be markets.
Draghi recognizes that “inconsistent and restrictive regulations” have inhibited innovators from commercializing their ideas, and he acknowledges that an “excessive regulatory and administrative burden can hinder the competitiveness of EU companies,” but his response leans toward a rationalization of regulation rather than its removal.
Thus, in his speech to the European Parliament introducing the report, Draghi talked of “encouraging innovative start-ups to scale up in Europe by removing regulatory hurdles,” but:
This is not about deregulation: it is about ensuring the right balance between caution and innovation, and ensuring that regulation is consistently applied within Europe.
Oh.
The EU that takes pride in being a “regulatory superpower” is not going to indulge in a deregulatory binge, and Draghi, a Brussels man, knows it. And Draghi’s fealty to “ever closer union” must raise suspicions that some of the “more Europe” he recommends owes as much to politics as to economics. In 1978, long before Rahm Emanuel was advising against letting “a serious crisis go to waste,” Jean Monnet, the most important of the EU’s “founding fathers,” wrote that “Europe will be forged in crises, and will be the sum of the solutions adopted for those crises.” And so this has proven to be. Monnet, like Emanuel understood, that (to use a term popular in Brussels) that a “beneficial crisis”could be exploited to force through changes that Europe’s democratically elected politicians would otherwise reject.
Gregg warns that “more Europe” will involve “giving more power with less accountability to those very same EU institutions that have promulgated so many of the regulations presently crushing European businesses.” The idea that, chastened by the damage caused by their overreach, those institutions will change their ways is laughable.
Draghi shows little sign of being willing to encourage the EU to junk its unhelpful ideological traditions. There must be change, but the bloc must also preserve its “values of equity and social inclusion.” Changes should be the product of a consensus arrived at through a “social dialogue”between different interest groups (such as “trade unions, employers and civil society actors”), thinking that Gregg ties to corporatism, an ideology with ancient roots on the continent. The quest for this type of consensus (“competition-crushing,” as Gregg rightly describes it) is designed to preserve a dismayingly static form of social harmony. Any reforms that emerge will be too limited, too few, and too late. This will leave the EU facing the prospect not of relative, but absolute, decline, something rarely associated with harmony of any kind.
Extract from The Capital Letter for the week beginning October 28, 2024